The Policyholder the Regulator Could Not See: Building a Clearer Picture of Insurance Inclusion
1. Executive Summary
An insurance regulator received reports showing approximately 800,000 policies across the market. However, the figure could not answer a fundamental question: how many unique people were actually insured?
A single customer might hold motor, health and life policies with several companies. Another policyholder might appear more than once because their name or identification information had been recorded differently. At the same time, millions of citizens could remain uninsured despite apparent growth in policy volumes.
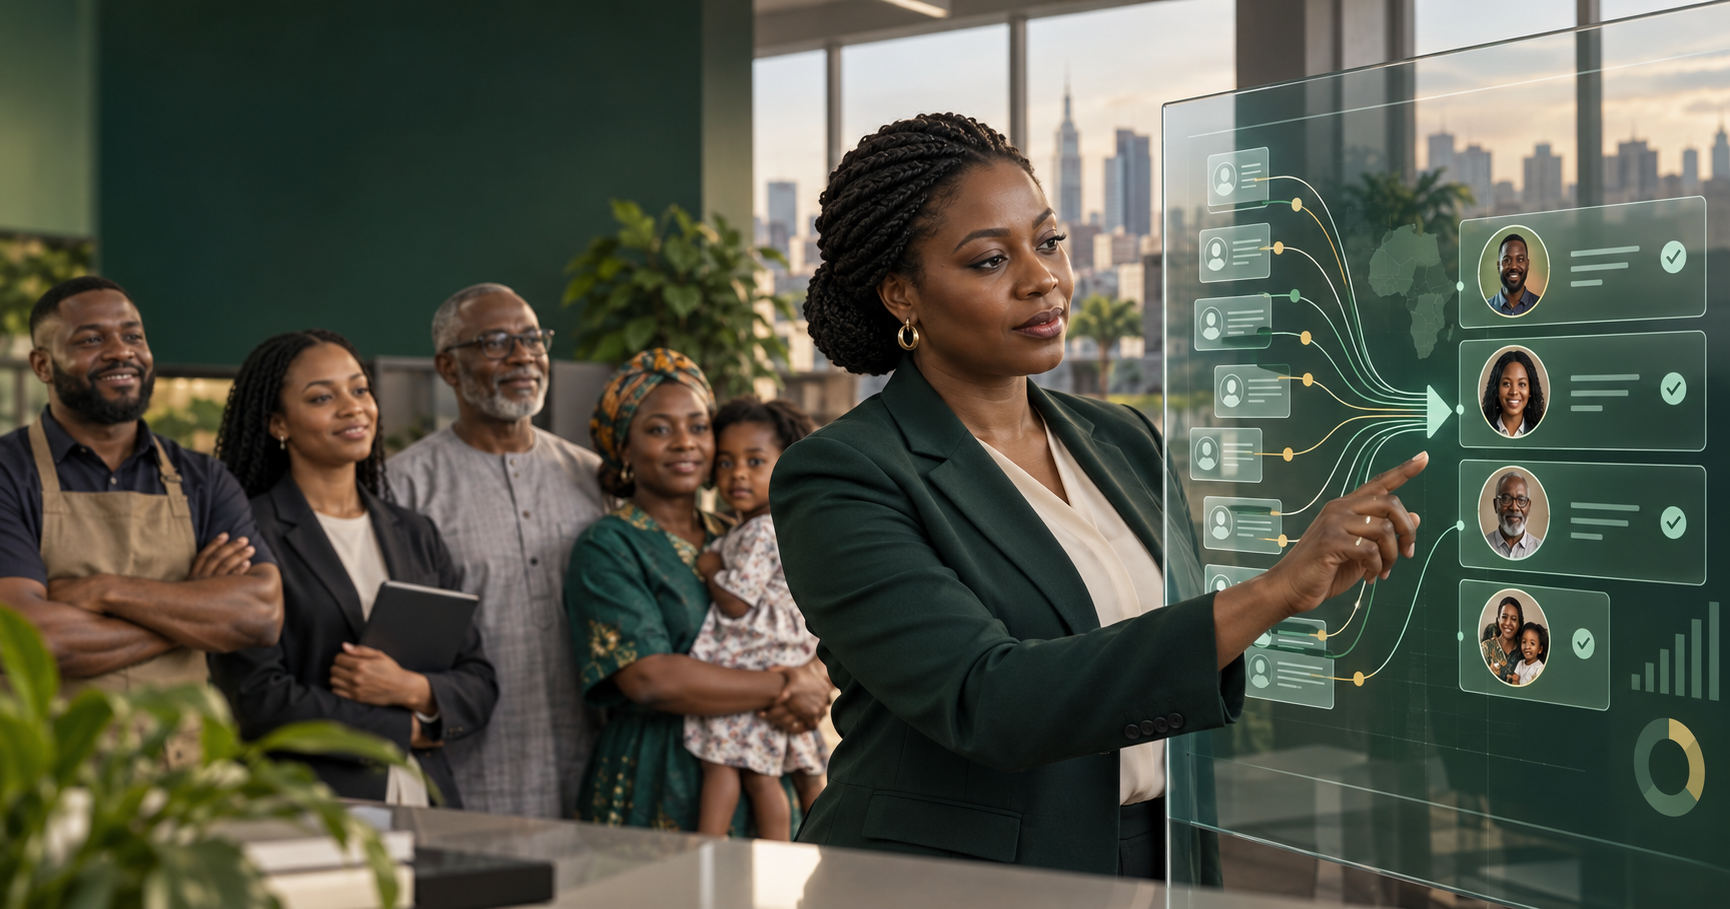
InsureGov would introduce a Unique Insurance Identifier for every verified policyholder. By connecting authorised policy records to a consistent identity, the regulator could distinguish between the number of policies issued and the number of people protected.
This would create a more reliable baseline for measuring market penetration, identifying underserved segments and evaluating whether inclusion initiatives were reaching new customers.
2. Background / Introduction
Insurance growth is often described using gross written premiums, policy counts, claims volumes and the number of licensed industry participants. These indicators remain important, but they do not always reveal whether the market is reaching more people.
If one policyholder owns five policies, the industry has recorded five contracts but only one insured individual. If the same customer’s name appears differently across multiple systems, that individual may be counted several times. Conversely, customers without formal identity documentation or consistent records may remain absent from industry analysis.
A fragmented identity environment can therefore create a false picture of progress. Policy volumes may increase while large parts of the population remain outside the insurance system.
3. Problem Statement / Challenge
The regulator relied on returns submitted by multiple insurers, brokers and other market participants. Each organisation maintained its own customer records and applied its own data-entry conventions.
The same policyholder could appear as “Deborah Namusoke” in one system, “D. Namusoke” in another and “Deborah N.” in a third. Without a shared identity reference, the regulator could not confidently determine whether these records represented one individual or several people.
This created several limitations:
- Reported policy counts could include duplicate policyholders.
- The number of uniquely insured citizens remained uncertain.
- Coverage gaps by location or customer segment were difficult to identify.
- The impact of microinsurance and inclusion programmes was harder to measure.
- Insurers had limited visibility into customers with policies across several companies.
- National growth targets were being assessed using incomplete identity information.
The absence of a trusted customer baseline affected regulatory planning, industry strategy and public communication.
4. Solution / Approach
InsureGov would establish a Unique Insurance Identifier for each verified policyholder. The identifier would act as a consistent reference across participating insurers without requiring those insurers to operate the same core system.
When a policyholder was onboarded, their identity would be verified against the approved national identity source. The platform would then determine whether the individual already had an insurance identity.
If a match existed, the new policy would be connected to the existing identifier. If no match existed, a new identifier would be generated.
InsureGov would subsequently:
- Link authorised policy records to verified policyholders.
- Identify probable duplicate customer records.
- Support the correction of inconsistent identity information.
- Separate policy volumes from unique policyholder counts.
- Aggregate appropriate data for regulatory analysis.
- Display inclusion and coverage indicators through a dashboard.
- Maintain appropriate consent, access and data-protection controls.
The regulator could then analyse market participation without relying solely on names, policy numbers or company-specific customer references.
5. Results & Impact
With a shared insurance identifier, the regulator would gain a clearer view of who was being served by the market.
The expected impact includes:
- A verified count of unique policyholders.
- Greater accuracy in insurance-penetration reporting.
- Identification and resolution of duplicate customer records.
- Improved visibility into customers holding multiple policies.
- Better measurement of first-time insurance adoption.
- Clearer analysis of underserved customer groups.
- Stronger evidence for inclusion and literacy programmes.
- More reliable information for market-development planning.
The system could also help distinguish genuine expansion from growth driven by existing customers purchasing additional products.
A live pilot should measure the percentage of records matched to verified identities, the number of duplicates identified, the difference between total policies and unique policyholders, data completeness and changes in identified coverage gaps.
InsureGov should not be credited with immediately increasing insurance penetration. Its first contribution is to establish a trustworthy measurement foundation. Growth strategies can then be designed and evaluated using better information.
6. Lessons Learned / Conclusion
An industry cannot confidently close an inclusion gap it cannot accurately measure.
Policy counts indicate market activity, but verified policyholder data reveals whether insurance is reaching more people. By giving every policyholder a consistent insurance identity, InsureGov helps regulators move from assumptions about coverage to evidence-based market development.
The result is not merely a cleaner database. It is a clearer understanding of who is protected, who remains excluded and where the industry should focus next.