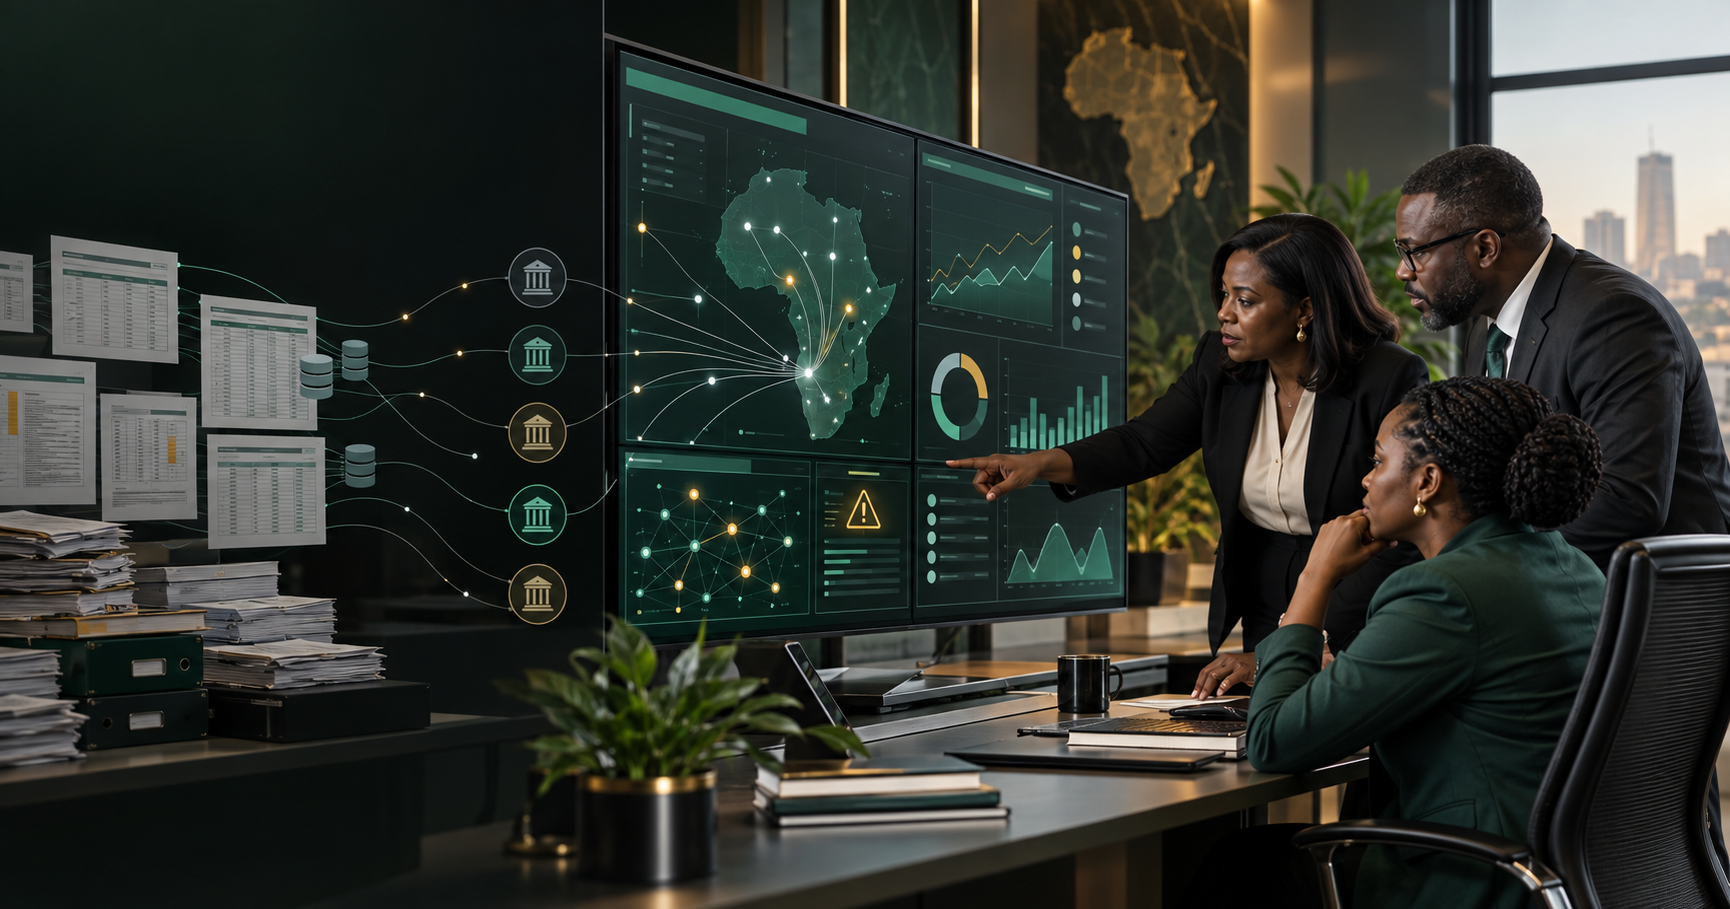
From Periodic Returns to Real-Time Supervision: Strengthening Regulatory Oversight with Connected Data
1. Executive Summary
An insurance regulator received returns from insurers, brokers and other licensed institutions at scheduled intervals. These reports were submitted in different formats and required extensive reconciliation before they could be analysed.
By the time an emerging risk appeared clearly in the data, several weeks or months might have passed. The regulator could identify historical problems but had limited ability to intervene while those risks were developing.
InsureGov would create a shared identity and data infrastructure through which authorised information could be standardised, validated and presented through a regulatory intelligence dashboard.
This would help the regulator monitor market activity more consistently, identify unusual patterns earlier and direct supervisory attention towards institutions or activities presenting the greatest risk.
2. Background / Introduction
Risk-Based Supervision requires regulators to understand the nature, scale and concentration of risk across the institutions they supervise. This depends on timely, complete and comparable information.
However, regulatory teams often receive information from institutions operating different systems and applying different data standards. Staff must review spreadsheets, reconcile inconsistent records and request corrections before meaningful analysis can begin.
The challenge becomes more significant as the number of market participants, policies, digital channels and product categories increases. Periodic reporting may remain necessary, but it provides only a snapshot of activity that has already occurred.
3. Problem Statement / Challenge
The regulator received information from underwriters, brokers, bancassurance providers and other licensed participants. Some reports arrived late. Others contained incomplete fields or customer records that could not be matched across institutions.
A sudden increase in claims within a particular segment might be visible to individual insurers but remain unclear at the market level. Similarly, an individual with several undisclosed high-risk policies could be difficult to identify when each policy existed in a separate system.
The regulator faced several operational constraints:
- Considerable time was spent cleaning and combining submissions.
- Institutions used inconsistent reporting formats.
- Customer records could not be reliably linked.
- Risk indicators were based largely on historical information.
- Compliance exceptions required manual investigation.
- Regulators had limited visibility into market-wide concentrations.
- Supervisory attention could not always be prioritised using current evidence.
These conditions made proactive supervision difficult.
4. Solution / Approach
InsureGov would provide a neutral infrastructure layer connecting identity, policy, claims and compliance information from authorised market participants.
Instead of depending entirely on disconnected returns, the regulator could receive standardised information through secure APIs or approved submission channels. Policyholder records would be connected to Unique Insurance Identifiers, improving the ability to resolve duplicates and identify relationships across institutions.
The platform would support:
- Standardised data requirements for participating institutions.
- Verification of policyholder identities.
- Secure policy and claims data exchange.
- Automated checks for missing or inconsistent fields.
- Configurable rules for regulatory and compliance monitoring.
- AML, sanctions and politically exposed person screening where applicable.
- Risk alerts based on unusual activity or threshold breaches.
- Dashboards showing market, institution and segment-level indicators.
- Complete audit records of submissions and supervisory activity.
The dashboard would support regulatory judgment rather than replace it. Alerts would identify areas requiring attention, while authorised officers would determine the appropriate supervisory response.
5. Results & Impact
The expected outcome would be a shift from heavily manual reporting towards more continuous and evidence-led oversight.
Potential benefits include:
- Faster consolidation of industry information.
- Improved completeness and consistency of regulatory data.
- Earlier identification of emerging risk patterns.
- Better prioritisation of supervisory resources.
- Greater visibility into policy and claims concentrations.
- More reliable monitoring of institutional compliance.
- Reduced dependence on repeated manual reconciliation.
- Stronger auditability of regulatory decisions.
- Better support for Risk-Based Supervision.
Pilot metrics should include submission-completion rates, time required to prepare industry reports, number of data-quality exceptions detected, percentage of policyholders linked to verified identities, time taken to review risk alerts and the number of institutions integrated.
The proposal describes a goal of achieving complete industry visibility. In practice, the level of visibility would depend on participation, data quality, integration coverage and the regulator’s reporting requirements. “100% visibility” should therefore be positioned as a full-adoption objective rather than an immediate result.
6. Lessons Learned / Conclusion
A regulator’s decisions are only as timely and reliable as the information supporting them. Moving from spreadsheets to a dashboard is not enough if the underlying identities and records remain inconsistent.
InsureGov combines regulatory reporting with a trusted identity foundation. This makes it possible to understand not only what is happening within individual institutions, but also how risks connect across the wider market.
The result is a regulator better equipped to identify risk earlier, focus its supervisory resources and protect the integrity of the insurance ecosystem.